Savings rates
Rates reviewed daily · last updated 5 October 2026
Savings rates
All rates AER · Updated October 2026
Rates shown are AER and correct as of October 2026.
Regular Saver
| Account | AER | Monthly Limit | Interest | Min Balance | |
|---|---|---|---|---|---|
| Regular Saver | 8.00% | £200 | Variable | £1 |
Easy Access
| Account | AER | Access | Interest | Min Balance | |
|---|---|---|---|---|---|
| Santander Edge Saver | 6.00% | Instant | Variable | £1 | |
| First Home Saver | 4.00% | Limited (higher rate in calendar months with 2 or fewer withdrawals) | variable | £1 | |
| Limited Access Saver | 3.00% | Limited (max 2/month) | Variable | £1 | |
| Select Easy Access Saver | 2.50% | Instant | Variable | £1 | |
| Easy Access Saver | 2.00% | Instant | Variable | £1 |
Cash ISA
| Account | AER | Access | Transfers in | Min Balance | |
|---|---|---|---|---|---|
| 5 Year Fixed Rate ISA | 4.90% | 5 Years | Accepted | £500 | |
| 3 Year Fixed Rate ISA | 4.85% | 3 Years | Accepted | £500 | |
| 2 Year Fixed Rate ISA | 4.80% | 2 Years | Accepted | £500 | |
| 1 Year Fixed Rate ISA | 4.65% | 1 Year | Accepted | £500 | |
| Inheritance ISA | 2.45% | Restricted eligibility (Additional Permitted Subscription holders only) | Not accepted | £0 | |
| Easy Access ISA | 2.00% | Instant | Accepted | £500 |
Fixed Rate
| Account | AER | Term | Interest paid | Min Balance | |
|---|---|---|---|---|---|
| 2 Year Fixed Term Saver | 4.70% | 2 Years | Monthly/Annually | £500 | |
| 3 Year Fixed Term Saver | 4.70% | 3 Years | Monthly/Annually | £500 | |
| Fixed Term Saver 1 Year | 4.45% | 1 Year | Monthly/Annually | £500 |
Junior ISA
| Account | AER | Access | Interest paid | Min Balance | |
|---|---|---|---|---|---|
| Junior ISA | 2.70% | Locked until 18 | Annually | £1 |
Investing: Stocks & Shares ISA
A Stocks & Shares ISA is an investment product, so returns depend on the market rather than a fixed savings rate. Here's how it compares on cost.
When you invest, your capital is at risk — the value of investments can go down as well as up, and you may get back less than you put in.
Cards
The Santander cards we track. Open one for fees, perks and the catch.
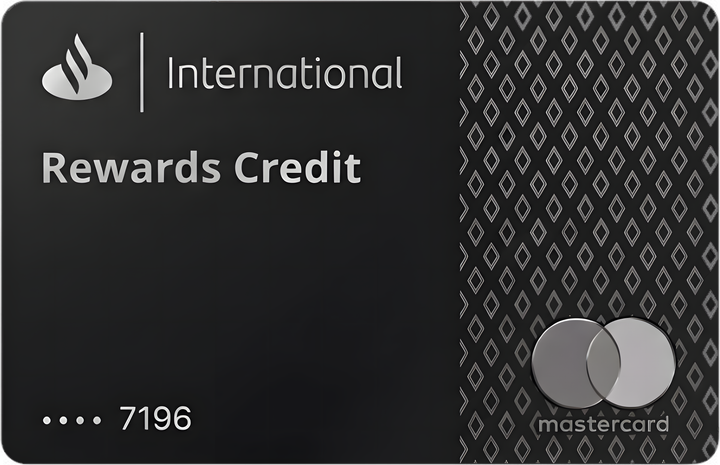
Rewards
Free
3% selected categories yr1; 0.25% other spend
- Abroad
- Fee-free spending
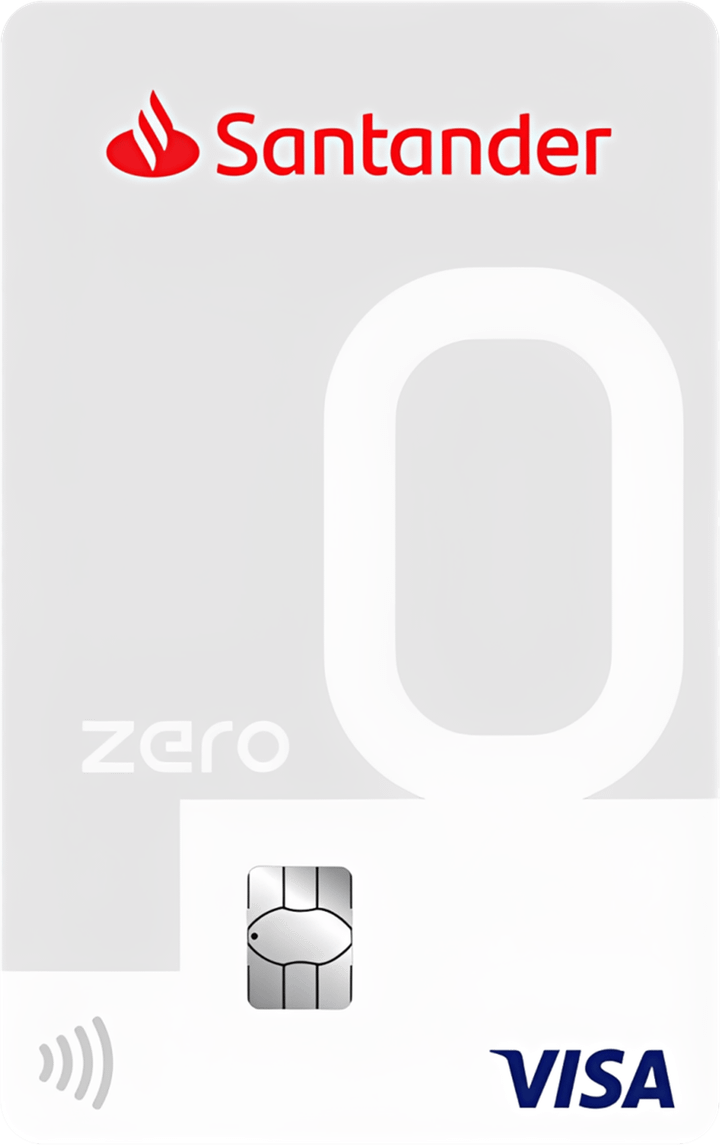
Zero
Free
The everyday card for spending abroad
- Abroad
- Fee-free spending
All in One
£3 per month
0.5% cashback capped at £10 per month
- Yearly cost
- £36
- Abroad
- Fee-free spending
Edge
£3 per month
Built for spending abroad
- Yearly cost
- £36
- Abroad
- Fee-free spending
World Elite Mastercard
£15 per month
0.5% cashback on all purchases
- Yearly cost
- £180
- Lounge access
- Included
Edge Explorer
£17 per month
Travel, phone and breakdown cover — plus the extras
- Yearly cost
- £204
- Abroad
- Fee-free spendingFee-free withdrawals
Is Santander FSCS protected?
Yes — FSCS protected up to £120,000
Yes. Santander savings are FSCS protected up to £120,000 per person, per banking licence, under Santander UK plc. The same limit is shared with Cahoot.
Banking licence: Santander UK plc
Shares this limit with Cahoot.
Last checked against the FCA register on 5 October 2026.
See every brand that shares a banking licenceSwitch offers
- Open an Everyday Current Account.
- Request a switch before 7 October 2026 using the Current Account Switch Service.
- Complete the switch within 60 days of your request, have at least 2 qualifying household Direct Debits and pay in £1,500.
- Within 60 days of your switch request, fund a Santander Regular Saver held in your name with at least £200
Who they are
Santander UK is a British bank, wholly owned by Banco Santander, the Spanish banking group. Its roots in the UK go back considerably further than the brand name suggests. The bank was built from three former mutual building societies - Abbey National, Alliance and Leicester, and Bradford and Bingley - with Abbey National bought by Santander in 2004 and the other two absorbed during the 2008 financial crisis. Abbey National and the savings business and branches of Bradford and Bingley were rebranded as Santander in January 2010. More recently, Santander agreed to acquire TSB from Sabadell for £2.65 billion, with that sale completing in April 2026.
Santander UK is authorised and regulated in the UK as a separate entity from its Spanish parent. Your deposits are protected by the FSCS up to £120,000. One thing worth knowing: Santander UK shares its banking licence with Cahoot, the online-only brand also owned by Santander. If you hold money with both, the £120,000 limit applies to the combined balance, not to each brand separately.
Savings accounts
Santander has one of the broadest savings ranges on the high street. The headline account is the Edge Saver, which currently pays 6.00% AER variable - but read the small print carefully. That rate applies only to balances up to £4,000, includes a variable bonus element that runs for the first 12 months only, and requires a Santander Edge current account to qualify. Once the bonus period ends, the rate drops back to a lower base variable rate.
For regular monthly savers, the Regular Saver pays 8.00% AER variable. That headline looks striking, but because you drip money in each month rather than depositing a lump sum, the actual interest earned over a year is much lower than the percentage implies - and you will need a Santander current account to open it.
Beyond those two, there is a Limited Access Saver at 3.00% (with a cap of two withdrawals per month), a First Home Saver at 4.00% for those building towards a property purchase, and a straightforward Easy Access Saver at 2.00% with no conditions attached.
For fixed-rate savings, the Fixed Term Saver range currently offers 4.45% for one year, 4.70% for two years, and 4.70% for three years. On the ISA side, there are fixed-rate Cash ISAs running from 4.65% at one year through to 4.90% at five years, all requiring a minimum of £500. The Easy Access ISA pays 2.00% variable, and there is also a Junior ISA paying 2.70% variable. All deposit-based accounts here carry FSCS protection up to £120,000.
Santander also offers a Stocks and Shares Investment ISA. Investments in that product are covered by the FSCS up to £85,000 if Santander fails - not the £120,000 deposit limit - and market losses are never covered by the scheme.
Switching to Santander
There is currently a cash incentive to switch your current account. Santander is offering £240 to new customers who open an Everyday Current Account, switch using the Current Account Switch Service, and meet a set of qualifying conditions: you need to request the switch before 7 October 2026, complete it within 60 days, have at least two qualifying household Direct Debits, pay in £1,500, and fund a Santander Regular Saver with at least £200 within 60 days of your switch request. The Everyday Account carries no monthly fee. The deadline for requesting a switch is 7 October 2026, so time is short if you are interested.
Is it right for you?
Santander suits savers who are already Santander current account holders, or who are willing to switch - the best rates here are gated behind having one of their accounts. The Edge Saver and Regular Saver are genuinely competitive headline rates for small balances and monthly saving, but both come with conditions that reduce their real-world value. For straightforward, no-strings easy access savings, Santander's base rates are unspectacular by market standards. The fixed-rate ISA range, by contrast, is solid and worth a look if you want to shelter interest from tax and prefer a familiar high-street name.
Rates on all products change over time - check the live figures on this page before making any decisions.
This overview was generated by DepositScout's AI, Penny on 5 October 2026. It may contain inaccuracies — always confirm rates and terms with Santander directly. Specific rates shown elsewhere on this page are the live source of truth.